“Rent is money down the drain” is one of the most repeated lines in Indian households — usually from someone urging you to buy a house. But is it actually true once you run the numbers? With home loan rates and rental yields both shifting in 2026, the home loan EMI vs rent decision deserves more than a gut feeling. Let’s break down the real math, the tax rules, and the factors that numbers alone can’t capture.
The Real Cost Comparison: EMI vs Rent in 2026
As of 2026, the RBI repo rate stands at 5.25%, keeping home loan interest rates in the 7.1%–8.5% range depending on the lender and your credit profile. Meanwhile, residential rental yields across major Indian cities remain in the 2.5%–4% range — a gap that has defined the buy-vs-rent debate in India for years.
Here are the assumptions used for the example below:
Assumption | Value Used |
Property value | ₹60,00,000 |
Down payment | 20% (₹12,00,000) |
Loan amount | ₹48,00,000 |
Home loan interest rate | 8.5% p.a. (2026 average) |
Loan tenure | 20 years |
Rental yield used | 3% (typical metro residential average) |
Assumed SIP/equity return | 12% CAGR |
Assumed property appreciation | 6% p.a. |
Sample Calculation: ₹60 Lakh Property
Using the assumptions above, here’s how the monthly outflow compares:
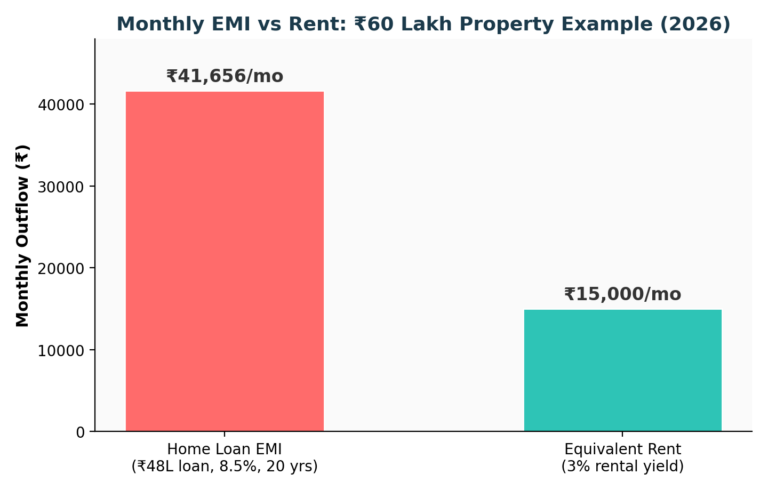
– Home loan EMI: approximately ₹41,656/month
– Equivalent rent (at 3% yield): approximately ₹15,000/month
– Monthly gap between EMI and rent: approximately ₹26,656
What If You Rent and Invest the Difference?
This is the crux of the buy-vs-rent debate. If you rent instead of buying, you free up two things: the down payment (which you’d otherwise put into the property) and the monthly gap between EMI and rent. Investing both consistently in an equity-oriented portfolio can build significant wealth over the same period.
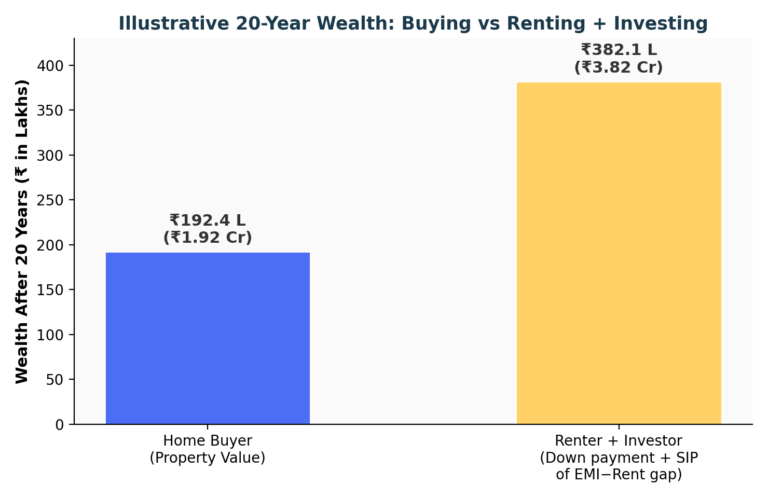
– Home buyer’s net worth after 20 years: property value grown to ~₹1.92 crore (at 6% annual appreciation), loan fully repaid
– Renter’s net worth after 20 years: down payment + monthly SIP of the EMI–rent gap grown to ~₹3.82 crore (at 12% CAGR)
On pure numbers, renting and investing the difference can outperform buying in this scenario — but this result is highly sensitive to the assumptions used. Lower equity returns, higher property appreciation, or a smaller EMI-rent gap in your city could easily flip this conclusion.
Home Loan Tax Benefits: Old vs New Regime
Old Tax Regime
Section 24(b): Up to ₹2 lakh deduction on home loan interest for a self-occupied property
Section 80C: Up to ₹1.5 lakh deduction on principal repayment (within the overall 80C limit)
New Tax Regime
No deduction available for self-occupied property interest or principal under the new regime
For a rented-out property, interest can still offset rental income, but the resulting loss cannot be set off against salary income — unlike the old regime, which allowed up to ₹2 lakh of such set-off
This makes the old regime meaningfully more attractive for existing or prospective home loan borrowers with a self-occupied property, so it’s worth running both regimes through a calculator before filing.
Factors Beyond the Numbers
Reasons to Buy
Stability and freedom from landlord-driven rent hikes or relocation notices
Forced savings discipline — EMI payments build equity, unlike rent
Emotional and social value of owning a home
Leverage: you control a large asset with a relatively small down payment
Reasons to Rent
Flexibility to relocate for jobs or lifestyle changes without selling an asset
Lower upfront capital requirement, freeing money for other investments
No exposure to property-specific risks like maintenance, disputes, or illiquidity
Ability to live in a better locality than you could currently afford to buy
Which Should You Choose in 2026?
– If you plan to stay in the same city for 7+ years and value stability, buying often makes sense despite the higher monthly outflow
– If your career involves frequent relocation or you’re still building your investment discipline, renting and investing the difference can be more efficient
– If you’re eligible for old-regime tax benefits and have a stable, long-term income, the EMI route becomes more attractive
– Either way, run your own numbers with your city’s actual rental yield and current home loan rate before deciding
Before committing to either path, it helps to have your investing habits in order.
For current repo rate and monetary policy updates, refer to the RBI Monetary Policy page, and for home loan tax provisions, see the Income Tax Department portal.
Frequently Asked Questions (FAQs)
-
Q1. Is buying always better than renting in the long run?
Not necessarily — it depends heavily on rental yields, equity returns, and property appreciation in your specific city and timeframe.
-
Q2. Can I still get home loan tax benefits under the new tax regime?
Not for a self-occupied home. The new regime removes Section 24(b) and 80C benefits, though a rented-out property still gets limited interest set-off.
-
Q3. What's a reasonable EMI-to-income ratio before taking a home loan?
Most lenders and planners recommend keeping your EMI under 40% of your monthly take-home income for financial comfort.
-
Q4. Does renting mean I'm wasting money compared to buying?
No — rent buys housing flexibility just like EMI buys ownership. Renting only “wastes” money if the saved difference isn't invested consistently.
Conclusion
The home loan EMI vs rent debate doesn’t have a single right answer — it hinges on your city’s rental yield, your discipline as an investor, your career stability, and how much you value owning versus flexibility. The numbers in 2026 slightly favour disciplined renting-and-investing in high-cost, low-yield cities, but buying still wins on stability, leverage, and tax efficiency for many households. Run your own numbers before deciding, because your city, your income, and your goals will tilt this calculation in a very personal way.
👉 Not sure whether to buy or rent in your city? Let Unicorn Finances run the numbers for your exact situation.
Leave A Comment